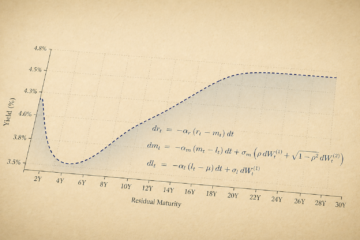
A Physics – Based Model of Returns: Anomalous Scaling and Irreversibility

Download PDF Abstract Every empirical study of financial returns since Mandelbrot (1963) has converged on the same short list of stylized facts: heavy polynomial tails, anomalous scaling of volatility with the aggregation horizon, power-law persistence of absolute returns, multiscaling across moment orders, and vanishing linear autocorrelation. These regularities are robust Read more…
Market Recap 03/05/2026

Download PDF USA U.S. equities extended their rally this week, with the S&P 500 (+0.9% w/w) and the Nasdaq Composite (+1.1% w/w) both closing at fresh record highs, as investors looked through a still-challenging macro backdrop and focused instead on a crucial earnings test for mega-cap tech. The week made Read more…

Attention Factors

Download PDF Introduction In this article we present a conditional latent factor approach to decompose US equities returns into systematic latent components and idiosyncratic residuals. The aim of the article is to expand on previous research by the Bocconi Student Investment Club by presenting an alternative approach to the traditional Read more…

Smile (and skew) for the camera!

Download PDF Introduction  Across different asset classes, volatility surfaces all tell different stories: in this article we let the data tell them unfiltered, building each surface directly on market quotes through interpolation rather than through the lens of a parametric model.  Implied volatility surfaces are among the most informative objects Read more…

Market Recap 19/04/2026

Download PDF USA US equity markets had a remarkable week. S&P 500 rose by 4.54% WoW, hitting a new record high on Wednesday, and DJIA grew by 3.20% WoW, jumping nearly 868 points in a single session. Marked by a swift de-escalation in the US-Iran tensions, markets have thus experienced Read more…